

Canada Set to Overtake China as Major U.S. Debt Holder
Canada has quietly become one of America’s biggest creditors, with the country on track to surpass China as a top-three holder of U.S. government debt before 2028.
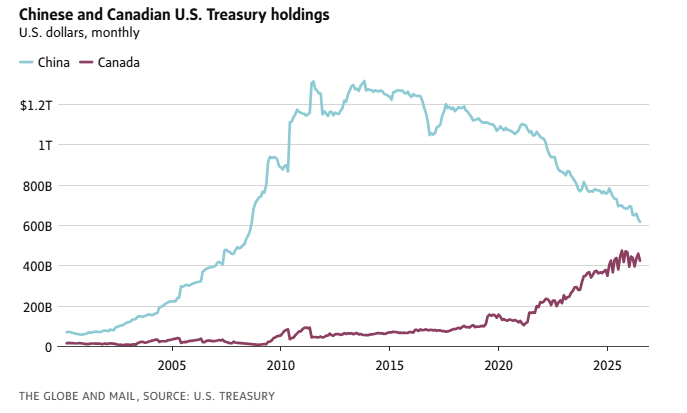
Roughly US$426-billion worth of U.S. treasury securities are currently held in Canadian accounts, up more than 300 per cent from US$106-billion in 2021. Bond market experts say part of that increase is simply the result of Canadian investors snapping up more treasuries as the interest rates, or yield, they offer has grown.
But the data includes all treasuries held in Canada-domiciled accounts, regardless of who owns them. That means Canadian holdings of U.S. treasuries can be controlled not only by domestic governments, institutions and individuals, but also by foreign entities. This has led some experts to believe Canada’s rapid rise in the ranks of U.S. creditors is at least partly a result of China moving its U.S. government debt holdings into Canadian-domiciled accounts, where it can retain control of the assets even as they are formally attributed to Canada.
Officially, Chinese holdings of U.S. treasuries have plummeted roughly 40 per cent to barely US$600-billion from more than US$1-trillion in 2021. However, China is widely known to use intermediaries in other countries – most notably Belgium – to hold treasuries, according to Tiffany Wilding, an economist at Pacific Investment Management Co. (Pimco).
“There is a background there that could suggest China certainly could have an intermediary take a treasury position in Canada,” Ms. Wilding said in an interview.
It is impossible to know for sure whether China is the driving force behind the rising U.S. treasury holdings in Canada. That is partly because the data itself suffer from “custodial bias,” where holdings are attributed to the country where the assets are held, as opposed to the country where the ultimate owner of those assets are based.
The possibility of China being the source of this activity makes it additionally challenging to confirm. While the country’s State Administration of Foreign Exchange (SAFE) releases breakdowns by country of international investments of its banks, non-bank financial institutions and the non-financial sector, details of the government’s official foreign exchange allocations are considered a state secret.
SAFE data showed that the China’s international investments totalled US$1.99-trillion at the end of 2025. Chinese investment in foreign debt securities stood at US$724.7-billion, of which US$198.7-billion were U.S. debt securities.
With Chinese bonds yielding far less than their U.S. equivalents – the yield on 10-year Chinese government bonds stood at 1.66 per cent on Friday, compared with a 5.11 per cent yield on the U.S. 10-year bond – there is a disconnect between the drop in China’s official holdings and the strong demand for U.S. bonds in China.
A Shanghai-based asset manager, who The Globe agreed not to name because he is not authorized to speak publicly, said the spread between U.S. and Chinese yields is a driver for asset managers to seek every tunnel to get access to the U.S. bond market.
China’s involvement “helps explain a lot of what is going on,” said Doug Porter, chief economist at Bank of Montreal, who noted Canada was on pace to surpass China as a U.S. treasury holder in a report published in late August.
Canadian holdings of U.S. treasuries are set to eclipse those of Belgium and China within 18 months, his report said, at which point only Japan and Britain will possess larger reserves of U.S. government debt.
“China is still investing in treasuries, just through other avenues,” Mr. Porter said in an interview. “I think a lot of people had long suspected that. What is interesting is that some of that is being done through Canada.”
Why China would want to obscure the true state of its U.S. treasury holdings is an open question. There could be political reasons, such as a desire to give the impression that China’s U.S. holdings are being reduced in response to continuing trade tensions.
Chinese law also classifies any plans to adjust foreign reserves, not just their overall composition, as a state secret. That would be a natural motivation to prevent any foreign entity – such as the U.S. Treasury Department – from accurately tracking the buying and selling of the country’s U.S. treasury holdings.
Whatever the reason, China would likely not be violating any laws by purchasing U.S. securities through intermediaries around the world.
“There is nothing nefarious here, it is just not through the traditional channels, and perhaps they don’t want to be seen as holding U.S. treasuries,” Mr. Porter said.
Some of the increase in Canadian holdings, he said, can be explained straightforwardly by investors who are actually based here buying more U.S. treasuries.
“There is some fundamental increased investment in U.S. treasuries by Canadian investors too. I think some of it is real,” he said.
“Some of the really large investors in Canada are looking at the kind of spreads they can get in the U.S. versus Canada, for instance.”
Derek Holt, head of capital markets economics at Bank of Nova Scotia, said in an e-mail that he was disinclined to believe China was the root cause of Canada’s climb up the U.S. foreign creditor ladder.
What is a more plausible explanation, he said, is the growing yield spread between U.S. treasuries and Canadian government bonds. Yield spread refers to the difference in expected return between two bonds with the same maturity. For example, the current yield for a Canadian government 10-year bond is roughly 1.25 percentage points lower than 10-year U.S. treasury notes, meaning buying the American security will generate a higher return.
“I’m not saying that I dismiss the China argument that it is spreading its holdings around,” Mr. Holt said. “But I wouldn’t have gone there first for plausible explanations of what we’ve seen.”
Pimco’s Ms. Wilding said another possible explanation for the rise in Canada’s U.S. treasury holdings is buying activity from Canada’s eight largest pension funds, known collectively as the Maple 8. Only two members of that group, the Ontario Teachers’ Pension Plan and the Caisse de dépôt et placement du Québec, publicly disclose their U.S. treasury investments.
The Caisse has doubled its holdings of U.S. treasuries to nearly $28-billion at the end of 2025 from roughly $14-billion at the end of 2021. OTPP data show its own positions have remained relatively unchanged. The other five major pension funds either declined to comment on their U.S. treasury holdings or did not respond.
“The OTPP data is a reasonable bellwether for the rest of the Maple 8 system, which suggests that they were not the ones to do this,” Ms. Wilding said.
“We are kind of scratching our heads on who it could be.”
This article was first reported by The Globe and Mail